Vilnius: The VAT reverse charge provisions that let member states shift tax liability to the buyer in fraud-prone sectors face a hard stop on 31 December 2026, when Articles 199a and 199b of the VAT Directive expire. Finance ministries and tax authorities now have less than three months to decide whether the optional scheme continues, and the decision will shape how Europe fights carousel fraud in 2027.
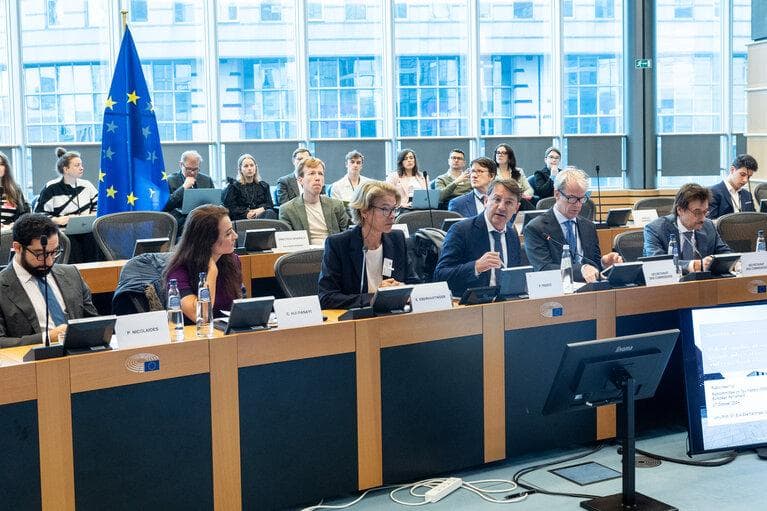
Parliament has already started the argument over the VAT reverse charge. Its tax subcommittee held a hearing on the two articles on 2 June 2026, and a draft report on VAT fraud and the reverse charge recommends extending Article 199a for about eight years. The Committee on Economic and Monetary Affairs is due to vote in the autumn, with a plenary vote pencilled in for 11 November 2026. That calendar leaves very little room for Council to react before the year ends.
The Council side is crowded. The Irish Presidency, which runs from 1 July to 31 December 2026, has listed several tax priorities: reaching agreement on the recast of the Directive on Administrative Cooperation, updating the EU list of non-cooperative jurisdictions in October, monitoring the minimum tax rules known as Pillar Two together with the side-by-side arrangement with the United States, and advancing any VAT proposals that reach the table. The VAT reverse charge deadline now competes with each of them for ministers’ attention.
Tax administrators were reminded of the stakes this week. The Tax Administration EU Summit, hosted by Revenue in Dublin on 6 and 7 October, brought officials together to compare tools for data sharing and compliance. The summit does not decide anything, but it shows how closely the fraud debate is tied to the data debate. A better exchange of information between authorities is exactly what the recast of the cooperation directive promises.
The longer VAT calendar adds context. The VAT in the Digital Age package, adopted in March 2025, starts to bite on 1 January 2027, when the one-stop shop widens to cover business-to-consumer supplies of electric vehicle charging. Digital reporting requirements for cross-border business transactions, with e-invoicing as the default, follow on 1 July 2030, and member states with domestic real-time reporting must align by 1 January 2035. Those reforms aim at the same fraud that the reverse charge tries to contain today.
Businesses should watch two dates. If Parliament votes on 11 November and Council agrees quickly, the VAT reverse charge could continue without a gap. If talks slip, traders in the affected sectors may face a change of invoicing rules on 1 January 2027 with little notice. The Tax omnibus the Commission planned for late June, which would amend six directives and arrive with a consolidated cooperation proposal, adds another moving part. For now, the only certainty is the expiry date, and the VAT reverse charge debate will be decided against that clock.