Luxembourg: Finance ministers took up the long-stalled tobacco taxation directive on 9 October 2026, when the Irish Presidency put the file back on the ECOFIN agenda after negotiators failed to agree a compromise text in June. The meeting in Luxembourg matters because the tobacco taxation directive is one of the few EU tax files where a single holdout can stop everything, and the current rules date from 2011.
This analysis explains why the revision keeps stalling, what the legal mechanics imply for 2026 and 2027, and what to watch once ministers leave the room.
Why the tobacco taxation directive keeps stalling
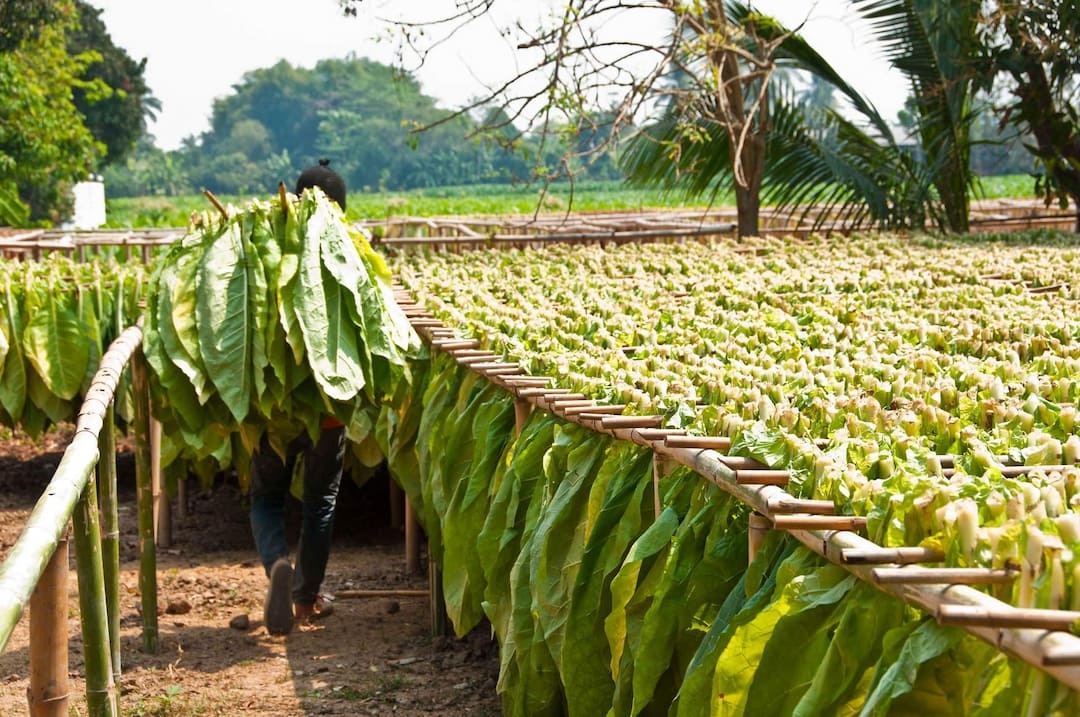
EU tax law moves by unanimity in the Council. The European Parliament is consulted, but it cannot force a result. That rule turns every tobacco excise negotiation into a bargaining exercise among 27 finance ministries with very different tax cultures, public-health priorities and domestic tobacco industries.
The Commission tabled its proposal to revise the framework in 2025. Its core logic was that the existing directive, built around cigarettes and cut tobacco, no longer reflects how nicotine is sold. Newer products such as vapes, heated tobacco and nicotine pouches sit in uneven national tax treatment, and that unevenness invites cross-border shopping and price arbitrage.
The June 2026 failure to reach a compromise showed that the problem is not a single clause. Capitals that depend on tobacco farming or manufacturing worry about minimum rates. Others with high national taxes worry about being undercut by neighbours. Both groups can be right at once, which is why a deal needs a package rather than a single concession.
What the Irish Presidency is trying to change
A presidency’s room for manoeuvre is narrow on tax files. It can reorder the text, split contentious items, offer longer transition periods and ask ministers to separate the question of rate floors from the question of product scope. Returning the file to ministers rather than to officials signals that technical work has run its course and that a political choice is now needed.
Ireland also has a domestic reason to care. It has some of the highest tobacco prices in the Union and a stated public-health goal of a smoke-free generation. A presidency with that profile can credibly argue that higher minimum duties are consistent with both revenue and health objectives, although it must act as an honest broker rather than an advocate.
Health and revenue pull in different directions
Tobacco excise serves two purposes that do not always align. Governments collect billions in revenue, yet the policy rationale for taxing tobacco is to reduce consumption. If higher duties succeed in cutting smoking, revenue per unit rises but volumes fall, so finance ministries plan cautiously and often favour long phase-ins.
Illicit trade complicates the picture. When legal prices rise sharply in one country and stay low next door, smuggling and cross-border purchasing grow. That is the strongest argument for a common floor, and it is why the Commission frames the tobacco taxation directive as an internal-market measure as much as a health measure.
Scenarios after the ECOFIN meeting
Three outcomes look plausible for the tobacco taxation directive. Ministers could reach a political agreement that leaves legal drafting for a later Council, which would be the best case. They could agree on a narrower set of principles and push the contested rate levels to 2027. Or the file could drift again, leaving the 2011 text in place while national governments legislate alone.
For businesses and public-health advocates the practical advice is the same. Track whether any compromise addresses product definitions first, because rates cannot be fixed until it is clear which products are covered. Track transition periods second, because they determine when price effects reach consumers.
Key takeaways
The tobacco taxation directive shows how unanimity shapes EU tax policy: reform is possible, but it arrives slowly and in packages. The 9 October ECOFIN discussion is a test of whether the Irish Presidency can convert months of technical work into political consent. Whatever the immediate outcome, the tobacco taxation directive will remain a benchmark for how far the Union can harmonise excise rules in 2026 and beyond, and a reminder that health ambitions in Brussels still depend on the tax calendar in 27 capitals.