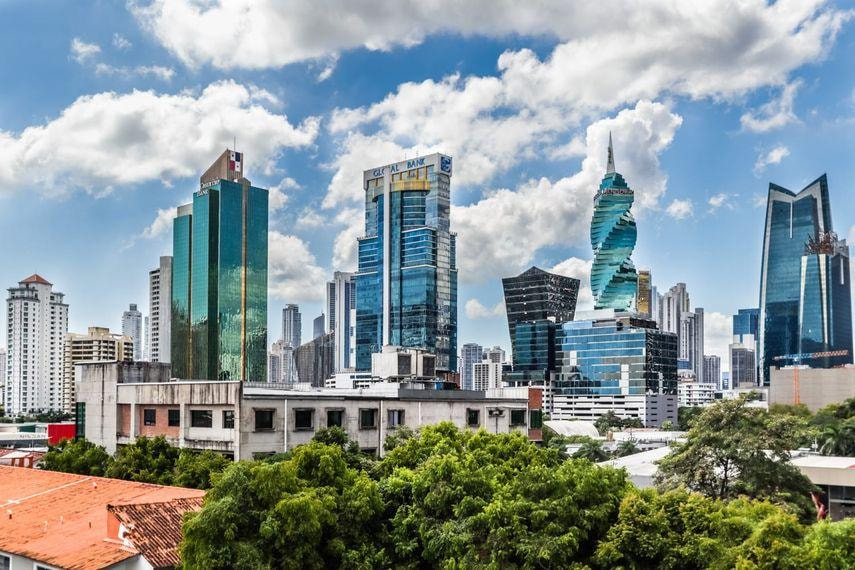
Panama City: The EU tax blacklist lost two names from its harshest tier on 9 October 2026, when finance ministers in the Economic and Financial Affairs Council approved the latest revision of the list of non-cooperative jurisdictions for tax purposes. Panama and Viet Nam moved from Annex I, the blacklist, to Annex II, the grey list, while Belize left the grey list altogether.
The Council moved Panama and Viet Nam while it waits for an in-depth review of their exchange of information frameworks by the Global Forum on Transparency and Exchange of Information for Tax Purposes. Belize exited Annex II after it met the international standard on exchange of information on request, a result that the Global Forum rated largely compliant. Montenegro stays under monitoring because it kept its commitment to an in-depth Global Forum review, but the Council wants to see the published outcome first.
Eight jurisdictions now sit on the EU tax blacklist: American Samoa, Anguilla, Guam, Palau, Russia, the Turks and Caicos Islands, the US Virgin Islands and Vanuatu. Vanuatu made progress on tax transparency but stays listed because of an outstanding concern in another area. Anguilla also remains after new worries emerged over its exchange of information framework, and the Council said it regrets that development and invited Anguilla to engage with the Code of Conduct Group and the Global Forum.
Annex II now holds ten jurisdictions: the British Virgin Islands, Brunei Darussalam, Eswatini, Greenland, Jordan, Montenegro, Morocco, Panama, Türkiye and Viet Nam. Brunei received more time, until 22 December 2026, to reform its foreign-source income exemption regime. Türkiye remains on the grey list because it does not exchange information with Cyprus.
The Council screens countries against three groups of criteria: tax transparency, fair taxation and the implementation of the OECD’s anti-base erosion and profit shifting standards. A place on the EU tax blacklist carries real consequences, because member states coordinate defensive tax measures against listed jurisdictions, and the EU tax blacklist also shapes how banks and investors price risk in those markets. The Commission, for its part, offers technical assistance to countries that want to leave the list. The revision takes effect once the Official Journal publishes the revised annexes.
The Council reviews the list twice a year, and the next update is expected in February 2027. That timetable gives Panama and Viet Nam about four months to satisfy the Global Forum reviewers, and it gives Anguilla and Vanuatu the same window to fix the issues that keep them in Annex I. Companies with subsidiaries in those places should watch the Global Forum publications as closely as the Council decisions.
For tax advisers, the October revision shows that the EU tax blacklist moves in both directions. A jurisdiction can leave quickly when it passes a peer review, and it can slide back when a new concern appears, as Anguilla found. The February update will show whether Panama and Viet Nam keep their place on the grey list or return to the blacklist.