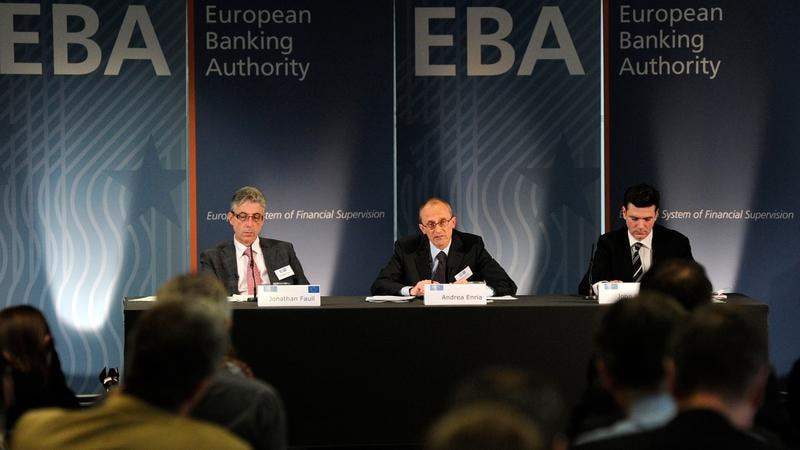
Frankfurt: The European Banking Authority published its EBA work programme for 2027 on 30 September 2026, setting out how the Paris-based regulator will spend its next year. The EBA work programme for 2027 leans on implementation rather than new headline rules, with the 2024 banking package, the new payment services framework and crisis management reforms at the top of the agenda.
According to a summary by the law firm Norton Rose Fulbright, the EBA lists nine priorities. These are finalising implementation of the 2024 banking package, applying the new payment services framework, supporting crisis management and deposit insurance reforms, and contributing to the Savings and Investments Union and securitisation agendas. The authority also plans to implement a new supervisory convergence framework, strengthen stress testing and simulation capacity, advance integrated reporting and data sharing, and reinforce its own governance and IT resilience.
A second theme is the authority’s growing remit over digital and market infrastructure. The EBA work programme for 2027 commits the agency to keep embedding its responsibilities under the Digital Operational Resilience Act, known as DORA, the Markets in Crypto-Assets Regulation, or MiCA, and the European Market Infrastructure Regulation, or EMIR. Each of these laws adds supervisory tasks that the EBA must deliver without a matching burst of new staff, which makes planning and prioritisation important.
For banks, the practical effect of the EBA work programme for 2027 is a steady flow of technical standards, guidelines and reporting templates tied to the banking package. Institutions that spent 2026 adapting capital rules will see the focus shift toward data quality and consistent supervision. Integrated reporting and data sharing, in particular, signal that the EBA wants fewer duplicate requests and more reuse of information across authorities.
Stress testing is another area to watch. The authority says it wants to enhance its stress testing and simulation capacity, which points toward more granular scenario analysis and closer links with crisis management tools. That fits the push on deposit insurance reform, where the EBA’s technical advice informs how national schemes and the resolution framework interact.
The available summary leaves several questions open. It gives no numbers on deliverables, consultations or budget, no deadlines for individual mandates and no direct quotes from the authority. The primary document on the EBA’s website will carry those details, and market participants should consult it before planning compliance work around the EBA work programme for 2027.
The wider significance of the EBA work programme for 2027 lies in sequencing. Lawmakers have produced a heavy volume of financial legislation since 2024, and the supervisory agencies now carry the burden of turning it into workable rules. How well the EBA work programme for 2027 balances those tasks with the Savings and Investments Union agenda will shape the pace at which European savers and companies see changes in banking and payments.


