Bratislava: Slovak retailers process a high share of card payments, and almost all of it travels through two American networks. That dependency, more than any enthusiasm for central bank technology, explains why the digital euro reached a trilogue table at all. It also explains why the hardest question left is not what the currency does but who gets to set its limits.
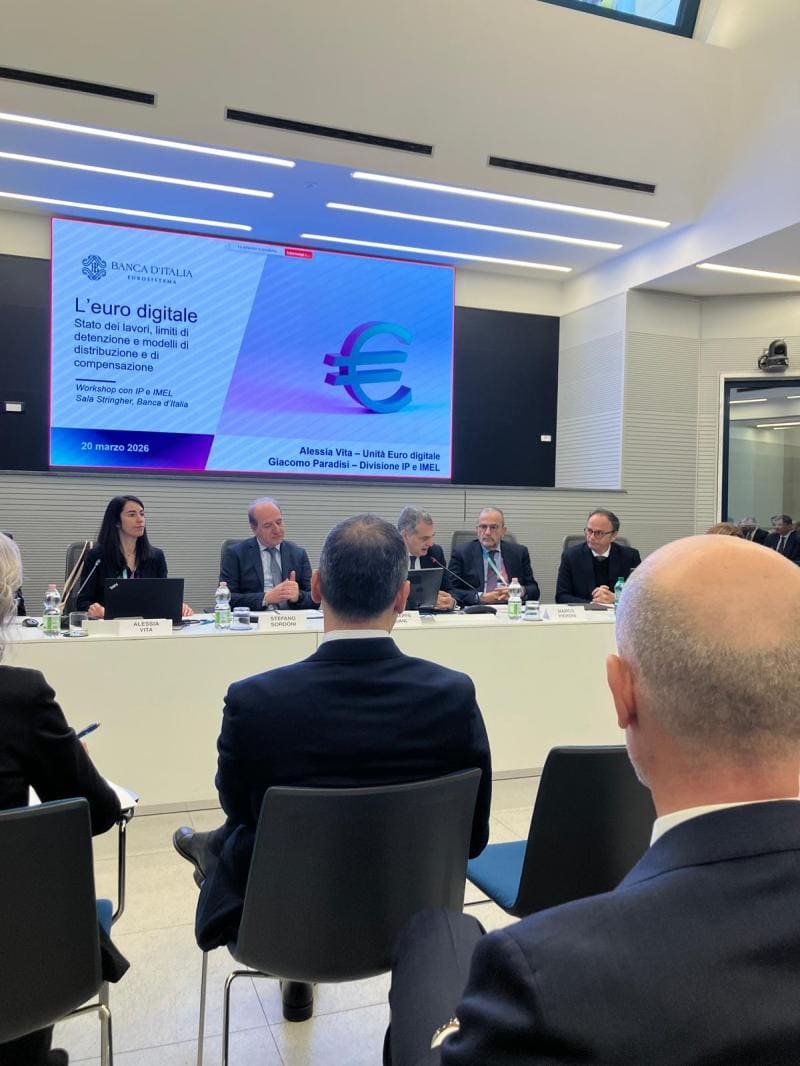
The file has moved faster than its critics expected. The Council fixed its position in December 2025. Parliament adopted its own in July 2026, and the first trilogue round followed days later, with all three institutions aiming to close the legislation before the end of the year. On the architecture there is broad agreement. On the holding limit there is not.
The holding limit caps how much digital euro any one person may keep. It exists because a central bank liability that anyone can hold in unlimited quantity competes directly with commercial bank deposits, and a nervous public could move money out of banks in hours rather than weeks. Every participant accepts the cap in principle. The fight is over the instrument that sets it.
Parliament wants the number fixed by delegated act, which keeps co-legislators in the loop and gives MEPs a veto they can actually use. The Council prefers an implementing decision, a route that leaves member states closer to the pen. Underneath sits a further disagreement about how much discretion the European Central Bank should hold, with some negotiators content to let the ECB calibrate the figure down to zero if financial stability demands it.
That sounds procedural. It is not. A cap set by delegated act moves slowly and publicly, which reassures banks but removes the flexibility a monetary authority wants during a deposit run. A cap the ECB can adjust at short notice does the opposite. The choice of legal instrument is therefore a choice about whether the digital euro behaves primarily as a payment product or primarily as a financial stability instrument, and the institutions have not said which they mean.
Banks have lobbied hard on this point and their argument carries weight. Deposits fund lending, and a cap that can rise quickly makes deposit bases harder to model. Consumer groups push the other way, noting that a low cap turns the digital euro into a novelty nobody bothers to use and leaves the original dependency on foreign card schemes untouched. Both cannot be satisfied by the same number.
Merchant costs form the second open front. The regulation contemplates a compensation model for acquirers and payment service providers, and the level at which those fees settle will decide whether shops accept the instrument willingly or treat acceptance as a legal chore. Privacy is the third, with offline functionality doing most of the work of answering the surveillance objection.
The Council has kept its negotiating detail closely held, which is normal at this stage and unhelpful for anyone trying to weigh the trade-offs. What is public supports one firm conclusion. Every figure named for the holding limit today is a negotiating position rather than applicable law, and reporting that treats a leaked number as settled policy is reporting a bargaining chip.
Issuance remains years away even if the regulation closes in December, because the ECB will not put a single digital euro into circulation before the legal base exists and the preparation phase concludes. The question this autumn decides is narrower and more durable than a launch date. It is who holds the dial.