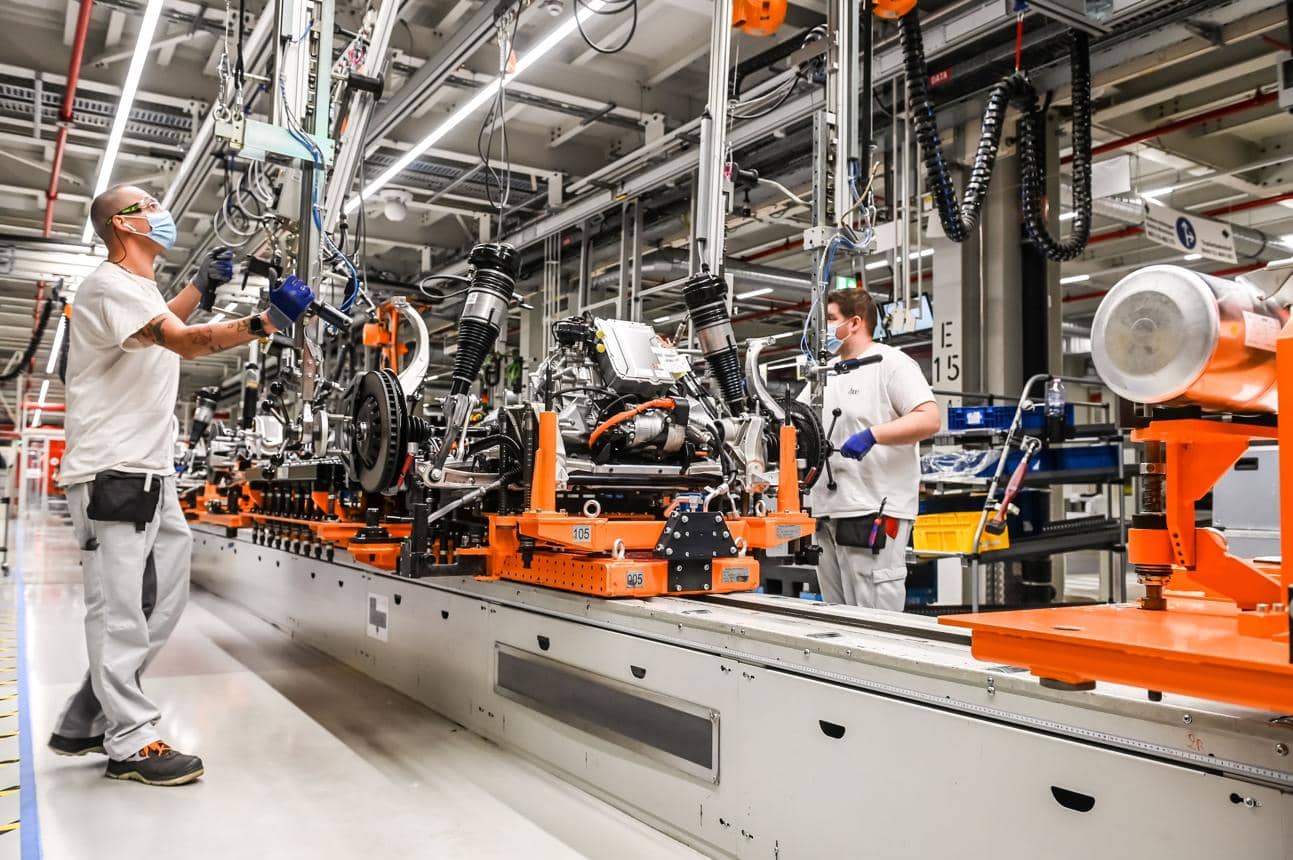
Euro area industrial production fell by 0.5% in August 2026 compared with July, and by 1.1% compared with August 2025, according to the Eurostat release of 15 October. In the wider European Union the monthly fall was 0.3% and the yearly fall 0.2%. The next reading, for September, is scheduled for 16 November, so the August figures remain the latest official verdict on how European factories are coping with the energy shock.
The sector breakdown shows a split economy behind euro area industrial production. Non-durable consumer goods dropped 2.7% in the month in the euro area and 9.1% over the year, the weakest result in the table. Intermediate goods fell 0.8% on the month, and energy output slipped 0.6%. Capital goods moved the other way, rising 0.4% on the month and 3.0% on the year, which suggests that investment-related production is holding up better than anything tied to household demand.
National figures swing widely. Belgium recorded the steepest monthly decline at 5.1%, followed by Ireland at 3.1% and Portugal at 2.0%. Sweden rose 6.5%, Estonia 4.3% and the Netherlands 2.6%. Over twelve months Ireland stands out with a fall of 15.0%, ahead of Belgium at 7.1% and Bulgaria at 5.4%, while the Netherlands gained 9.8%, Hungary 8.8% and Denmark 8.3%. Eurostat’s total industry index for the euro area stood at 97.5 in August, down from 98.0 in July, so output sits below the 2021 base year.
Prices tell the other half of the euro area industrial production story. Eurostat’s producer price release of 5 October put industrial producer prices up 1.9% in August from July in the euro area, and 8.2% above a year earlier. Energy drove the jump, with prices 21.0% higher than in August 2025. Strip energy out and the yearly rise falls to 3.4%, which still sits well above the pace policymakers would like. Factories are therefore producing less while paying far more for power, an uncomfortable mix for margins.
Consumers are not rescuing demand for factory output either. Retail trade volume rose just 0.1% in August and 0.8% over the year in the euro area, according to the 6 October release. Sales of automotive fuel in specialised stores fell 3.7% over the year, and have fallen every month since April, a sign that households are cutting back where prices bite hardest.
Analysts will read the next euro area industrial production release for three signals. The first is whether the August decline in intermediate goods repeats, because that category feeds later production. The second is whether consumer goods output stabilises after the sharp fall. The third is whether the divergence between capital goods and everything else persists, which would point to a recovery built on investment rather than spending.
The data also matter for policy. A shrinking industrial base alongside rising producer prices complicates the task for the European Central Bank and for the Commission. Weak output argues for support, while price pressure argues for caution. The 16 November release will show whether euro area industrial production stabilised in September or whether August was the start of a longer slide. Until then, the numbers point to an industrial sector under pressure from costs it cannot control and demand it cannot count on.