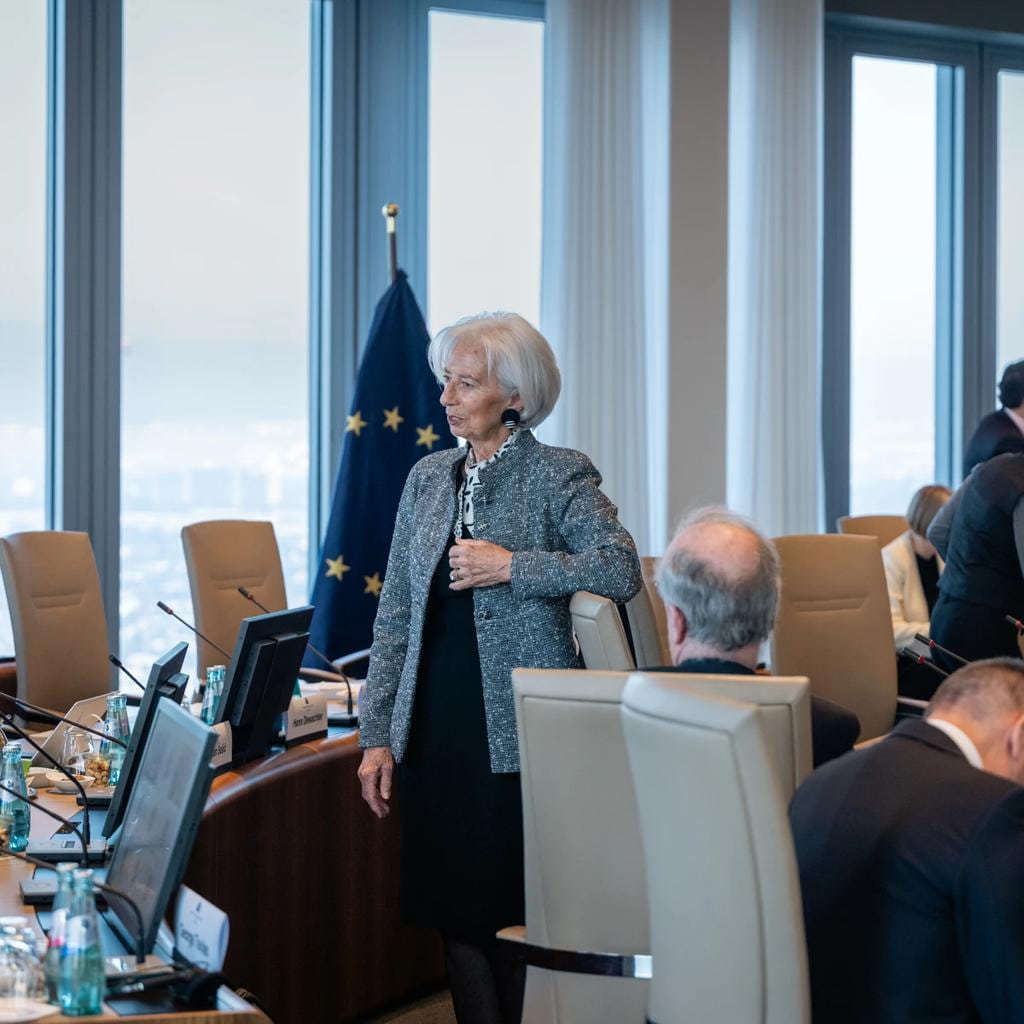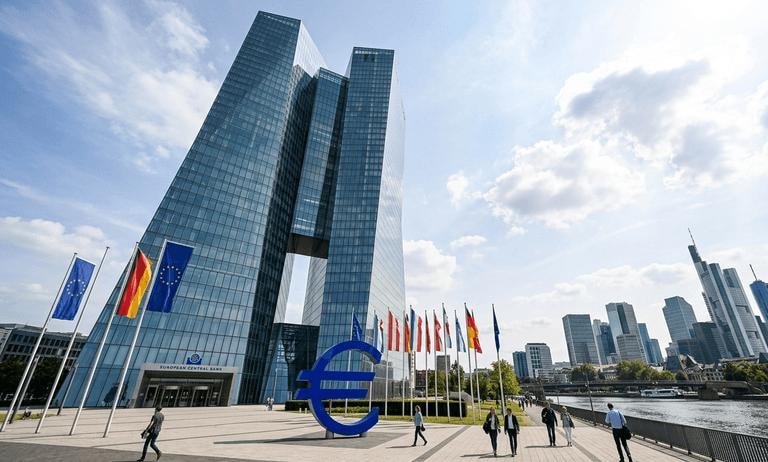
Frankfurt: The most consequential figure in European payments legislation has not been written down yet. It is the holding limit for the digital euro, the cap on how much central bank digital money any one person may keep, and it is the reason the file has taken three years to reach the stage it reached on 10 September.
Negotiators from the Parliament and the Council held their second political trilogue on the digital euro package that day, following technical meetings that had run since the start of the month. The Irish presidency wants political agreement before the end of the year, which would keep the European Central Bank on its stated path towards a pilot in the second half of 2027 and potential first issuance in 2029.
The holding limit is contested because it decides whose problem the digital euro is. Set it high and the instrument becomes a genuine alternative to a bank account, which is what its more enthusiastic supporters want: sovereign retail payment rails that do not depend on two American card networks. Set it high and you also create the possibility that in a period of stress, depositors move from commercial banks into a risk-free claim on the central bank, withdrawing the deposit funding on which bank lending rests. Banks have made that argument continuously and it is not merely self-serving; a digital run is faster than a physical one.
Set the limit low and the instrument is safe for the banking system and close to pointless for the user. A cap in the low hundreds of euro produces a payment method nobody keeps enough in to rely on. The ECB has argued the limit should be calibrated by the central bank rather than fixed in legislation, because the correct number depends on conditions that change. Legislators are reluctant to hand over a parameter of that significance without constraint, and a fight about who sets a number is usually a fight about who is accountable for it.
Two further issues sit alongside it. The compensation model determines what banks and payment service providers may charge merchants and each other for handling digital euro transactions, with a proposed cap designed to stop the new rails from simply reproducing the fee structure they are meant to discipline. Acceptance rules determine which merchants must take the digital euro, and the exemptions sought for very small businesses go to whether the instrument achieves the universality that gives legal tender status its meaning.
Parliament adopted its position earlier this year, framing the project in terms of monetary sovereignty and resilience in retail payments. The Council’s mandate is more cautious on limits and acceptance. That is the familiar shape of a trilogue and it usually resolves, but the schedule is tight. A regulation adopted in 2026 leaves the Eurosystem room to build. One adopted in 2027 does not, and the 2029 date starts to slip.
There is a wider point that the technical argument tends to obscure. The digital euro is being legislated at a moment when the case for it rests less on consumer demand, which remains modest, than on infrastructure dependence. Card payments in the euro area run largely on networks headquartered outside it, and dollar-denominated stablecoins are becoming a meaningful settlement medium. Neither of those developments is a crisis. Both are arguments for having a public option that works if the private ones become unavailable or unaffordable.
Whether that argument is strong enough to carry a difficult file through a compressed autumn is the question the next trilogue will start to answer.