The digital euro negotiations between Parliament and the Council have entered what officials describe as an intense phase, with the Irish Presidency aiming for a political agreement on 18 November 2026 if at all possible. After more than three years since the Commission’s June 2023 proposal, the remaining disputes concern money and control rather than principle.
How the digital euro negotiations reached this point
The Council agreed its mandate on 19 December 2025 under the Danish Presidency. Parliament’s Economic and Monetary Affairs Committee adopted its position on 23 June 2026 by 43 votes to 14, and the plenary confirmed the mandate on 9 July. Trilogues opened on 13 July, so the co-legislators have spent roughly four months reconciling two texts.
Both institutions accept an online and an offline digital euro. Neither makes the online version conditional on a private pan-European payment solution, a condition that once looked likely to survive. That shared ground matters, because it removes the most ideological dispute from the digital euro negotiations.
Holding limits and who decides them
Holding limits are the control point. Parliament wants the Commission to set the ceiling on advice from the European Central Bank, with a review at least every two years and Parliament keeping full review powers. The Council would set it through an implementing decision under reinforced qualified majority voting, again on ECB advice.
The treatment of businesses differs more sharply. Parliament favours a near-total ban on holdings by legal persons written into the regulation, whereas the Council leaves the matter to the ECB and hints at possible zero limits. Neither text names a figure, so the real number will emerge only after adoption.
Why merchant fees dominate the final stretch
Compensation is the hardest file. Both institutions want uniform fee caps across the euro area, starting with a transitional model and later moving to cost-based charges plus a margin. They disagree on duration. Parliament would let the transitional model continue indefinitely if a Commission report supports it, while the Council sets a ten-year maximum.
Merchant protection splits them again. Parliament wants caps for each merchant, and the Council prefers national caps that bite only where fees sit well below the uniform caps. France also opposes Parliament’s “no worse off” clause. Banks and payment providers watch these lines closely, because they decide who earns revenue from a public means of payment.
What remains technical and what remains political
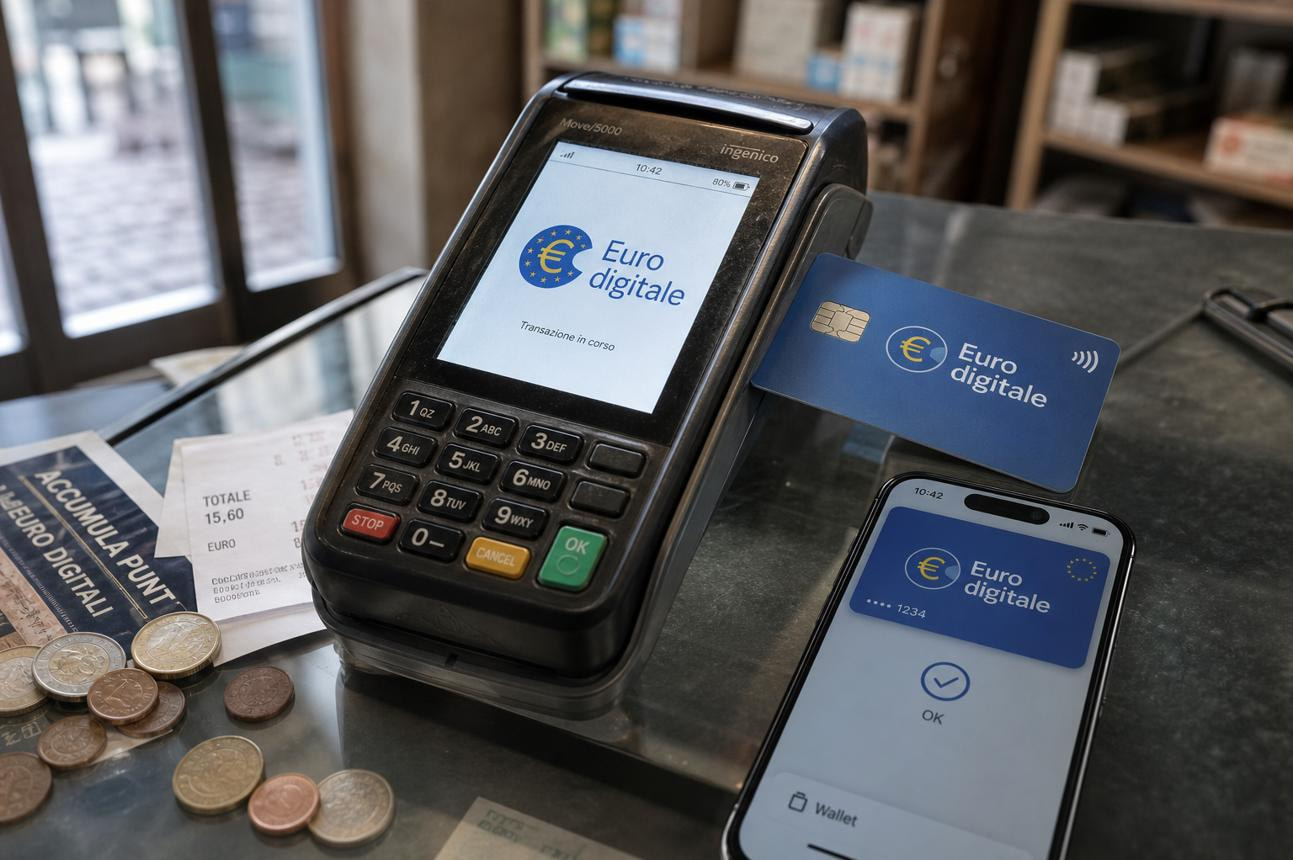
Some items look technical but carry political weight. The designation of payment service providers is still being worked out, and services for sanctioned persons, including officials of the International Criminal Court, await Commission guidance. Offline payments run on local storage devices, so a lost device means lost funds with no refund, a design choice that protects privacy at the cost of consumer recovery.
Basic accounts and offline payments would be free for users under Parliament’s position, which gives the project a social purpose beyond payments efficiency and raises the stakes of the digital euro negotiations for consumers.
What happens next
If the digital euro negotiations close on 18 November, lawyers will finalise the text and both institutions will vote in 2027. Rollout would follow at least 24 months after authorisation, with the ECB targeting operations by 2029 and a pilot involving 36 payment service providers from the second half of 2027.
A miss on 18 November would not end the project, but it would push the timetable towards a new presidency. The digital euro negotiations now hinge on whether Paris, the Parliament and the Council can agree a fee formula that merchants accept and banks tolerate.