The Pontes digital euro platform went live on 21 September, opening the Eurosystem’s first production channel for settling tokenised assets in central bank money. Thirteen banks and four distributed ledger operators are connected from day one. It is a wholesale system, restricted to credit institutions, and it is not the digital euro that consumers have been reading about.
## What the Pontes digital euro platform actually settles
Pontes links commercial distributed ledger platforms to Eurosystem settlement infrastructure. When a tokenised bond or fund unit changes hands on one of those ledgers, the cash leg settles in central bank money rather than in a commercial bank claim or a stablecoin.
That is the whole design intent. Tokenised securities markets have been growing in Europe without a risk-free settlement asset, which forced participants to accept counterparty exposure they would never tolerate in conventional markets.
Deutsche Bank and Santander are among the thirteen institutions live at launch, alongside four ledger operators including Clearstream, the Deutsche Boerse settlement arm. Operating hours run from 08:00 to 16:00 CET on business days, with the ECB saying hours and functions will widen over time.
## Why the ECB moved on wholesale before retail
Wholesale settlement needs no new legislation. The ECB can build it on existing Eurosystem competence, which is why Pontes could launch while the retail digital euro regulation is still moving through the Parliament and Council.
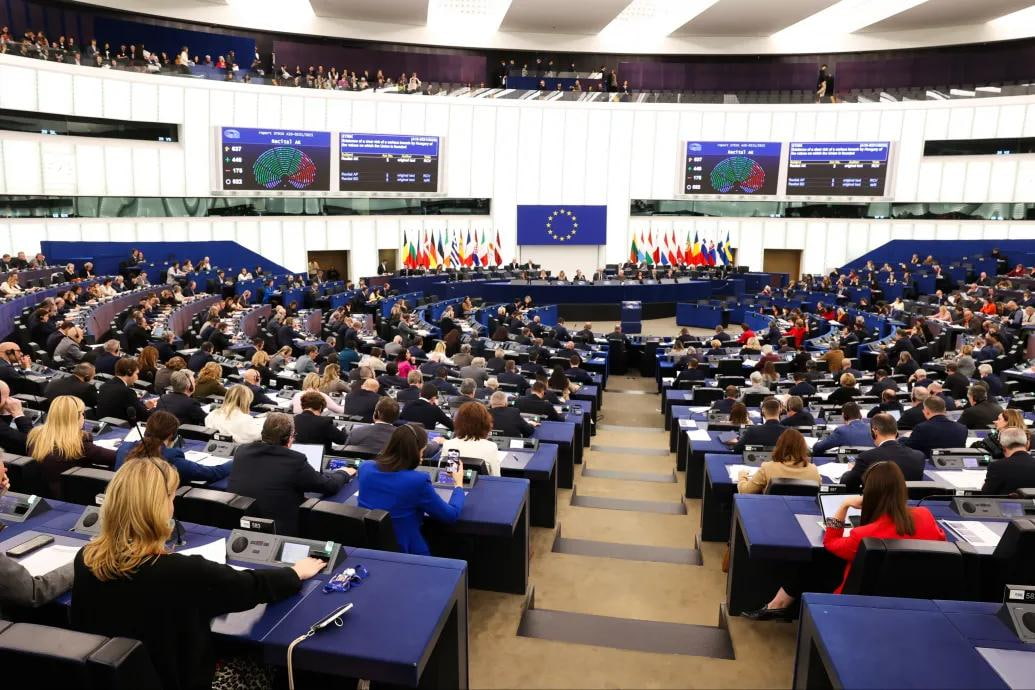
Christine Lagarde set out the sequencing at the Eurogroup on 18 September, telling ministers the ECB is waiting on the EU legislative process and intends to begin pilot testing around the middle of 2027. The retail project then runs a twelve-month pilot across the ECB and the nineteen euro area national central banks, with possible issuance in 2029.
The two tracks are genuinely separate. Pontes is plumbing between financial institutions. The retail digital euro is a payment instrument for households, with holding limits, distribution through banks and a political fight over both.
## What it means for Europe’s tokenised markets
The competitive subtext is stablecoins. Dollar-denominated tokens dominate on-chain settlement, and a euro settlement rail backed by the central bank is the most direct institutional answer available to the Eurosystem.
Three practical consequences follow for market participants:
– issuers gain a credible euro cash leg for tokenised debt, removing a standing objection from treasurers
– custodians and central securities depositories must decide how far to rebuild around ledger-native settlement
– national supervisors face early questions about how ledger operators outside the banking perimeter are overseen
Volume will be the honest measure. A platform with thirteen participants and an eight-hour window is a pilot in everything but name, and the ECB has not published throughput targets.
## Key takeaways
The launch matters less for what it settles this month than for what it forecloses. By putting central bank money on tokenised rails now, the Eurosystem makes it harder for a private settlement standard to entrench itself in euro markets before the retail digital euro even reaches a vote.
The risk runs the other way too. If the retail regulation stalls into 2027, as several finance ministries expect, the Union ends up with sophisticated wholesale infrastructure and no consumer-facing instrument, which is close to the position it was trying to escape.
For now, the Pontes digital euro platform gives Brussels something it has lacked in this debate: a working system rather than a consultation paper.