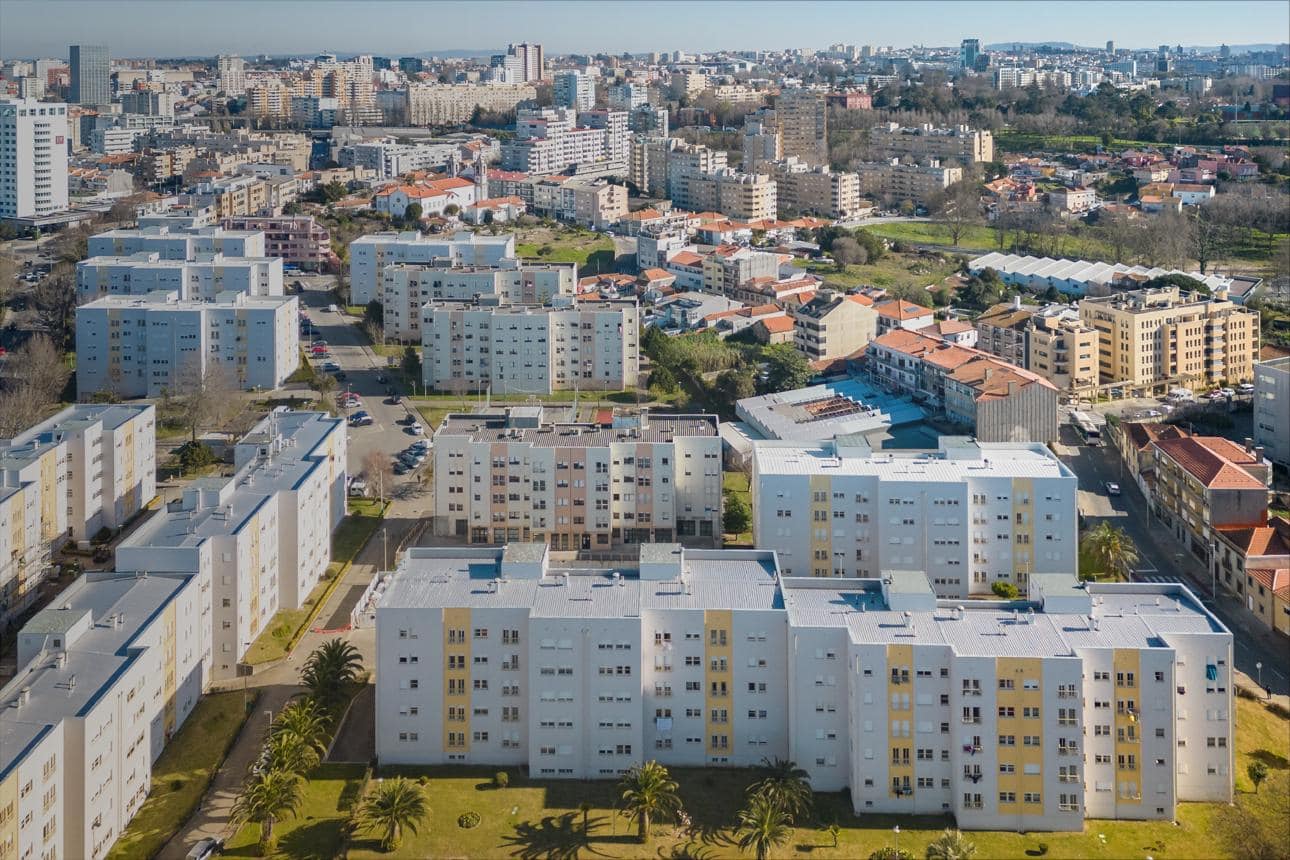
Porto: Eurostat data released on 9 November 2026 show that the EU house price to income ratio stood 6.8% higher in 2025 than in 2015, confirming that home prices have outrun household incomes over the past decade. The ratio rose in 17 Member States and fell in 10, leaving a sharply divided housing map across the Union.
Portugal tops the table by a wide margin. Its house price to income ratio jumped 60.8% between 2015 and 2025, far ahead of the Netherlands at 34.3%, Hungary at 26.5%, Czechia at 25.8% and Spain at 24.5%. Ireland ranked eighth, with an increase of about 13%.
Porto and Lisbon have become symbols of that Portuguese surge. Local buyers in both cities now compete in markets where prices have climbed far faster than wages, and the new statistics quantify the gap for national and European policymakers.
At the other end of the scale, Romania recorded the steepest fall, with its house price to income ratio down 42.8%. Finland followed with a drop of 25.2% and Bulgaria with 16.2%. Analysts caution that a falling ratio does not necessarily mean homes became cheaper in absolute terms. In many cases, incomes simply grew faster than prices.
Eurostat also compares the standardised ratio with its long-term average since 2000. On that measure, the EU peaked at 7.9% above average in 2007, just before the financial crisis, and again at 7.4% above average in 2022. The ratio sank to 6.4% below average in 2014, eased again in 2023 and 2024, and finished 2025 just 0.03% above its long-run mean.
That near-average EU reading hides large national differences, and those differences matter for policy. Italy, for example, posted a standardised score of 86.9 points in 2025 against a long-term benchmark of 100, up slightly from 85.6 in 2024 and 85.5 in 2023. Italian buyers therefore still face a relatively favourable house price to income ratio compared with buyers in Lisbon, Amsterdam or Budapest.
The new figures land as housing affordability climbs the EU agenda. Several governments face pressure from young voters priced out of home ownership, and the Commission has made housing a recurring theme in its economic guidance. Statistics on the house price to income ratio give ministers a common yardstick for comparing national pressures and for judging whether supply measures work.
The data also carry lessons for financial supervisors. A ratio far above its historical average can signal overvaluation and higher risks for banks that hold large mortgage books, especially when interest rates rise.
For households in Porto, Amsterdam or Prague, the numbers confirm what many already feel when they browse property listings. Unless incomes catch up or supply expands, the house price to income ratio in the hardest-hit Member States will remain a central test for national housing policy in the years ahead.